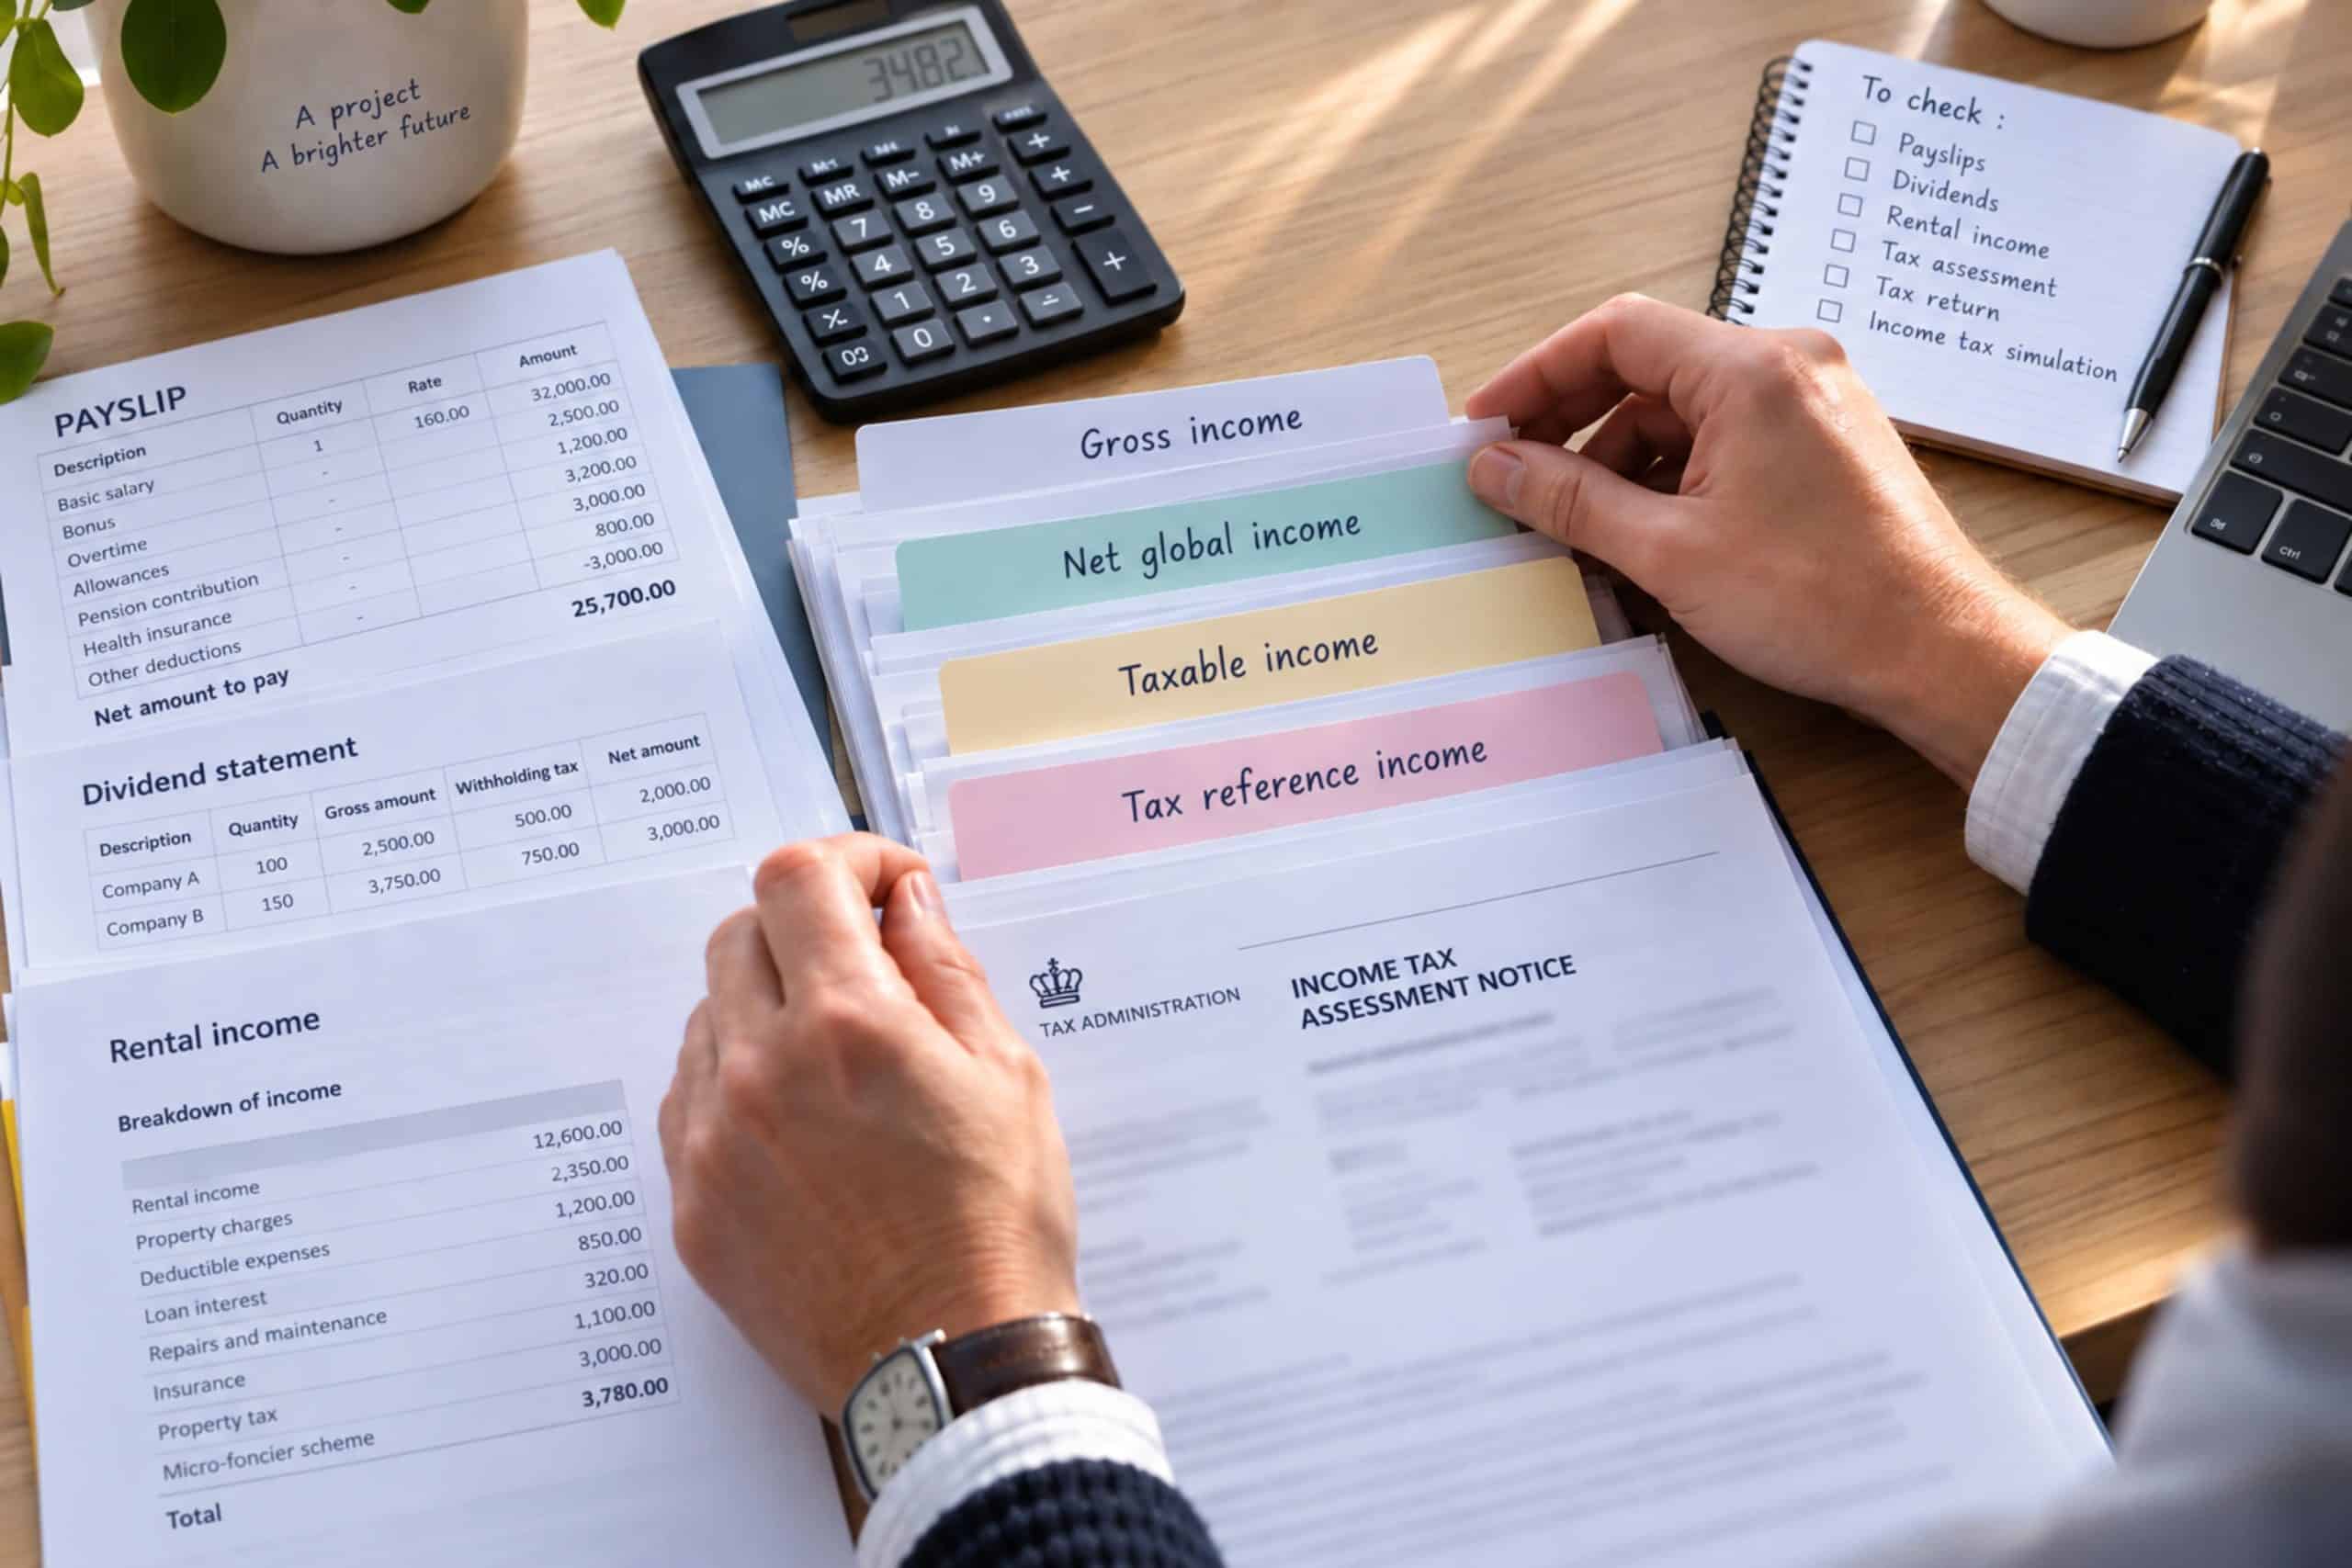


Total gross income, total net income, taxable net income or reference tax income: do you know what these terms cover? They correspond to different steps in the French income tax calculation and make it possible to establish your tax rights and obligations. Here’s an overview.
| Term | How it is obtained |
|---|---|
| Total gross income | The sum of your income, profits and gains for the year, after deductions |
| Total net income | Total gross income minus certain deductible expenses |
| Taxable net income | Total net income minus specific deductions |
| Reference tax income | Taxable net income plus certain income and allowances added back |
What is total gross income?
Total gross income corresponds to the sum of the income, profits and gains you received during a calendar year, after applying certain deductions (such as the 10% deduction on wages and pensions, for example).
It includes, among other things:
- taxable net wages,
- industrial and commercial profits (BIC), non-commercial profits (BNC), or agricultural profits (BA),
- dividends,
- pensions,
- rental income (income from real estate),
- other investment income and capital gains on securities,
- capital gains from real estate.
How is total net income calculated?
Total net income is obtained by subtracting certain expenses from total gross income.
These expenses include, among others:
- the deductible portion of the general social contribution (CSG) on wealth and investment income,
- alimony payments and contributions to household expenses,
- payments and premiums for retirement savings plans,
- benefits in kind provided to people over 75,
- expenses related to historic buildings and similar properties,
- contributions to the war veterans’ mutual pension fund,
- social security contributions and similar amounts not already deducted when determining categorized income,
- expenses for major repairs incurred by usufructuaries (without ownership rights) of properties received through inheritance or gift, for which an offer was accepted and a deposit paid before January 1, 2017 (this deduction has been abolished for expenses incurred by such usufructuaries since January 1, 2018),
- deductions under Articles 145 II and 156a of the French Tax Code (CGI).
What is taxable net income?
Taxable net income is obtained, in certain cases, by subtracting specific deductions from total net income.
These deductions relate to, among others:
- elderly people,
- people with disabilities,
- parents in cases where their married children or dependent children are attached to the household’s tax return.
Taxable net income and the progressive tax scale
Taxable net income is the income subject to the progressive income tax scale.
Income taxed at a flat rate (such as the single flat-rate withholding tax or the final withholding tax) is not included in this, unless taxation under the progressive scale has been chosen.
What is reference tax income?
Reference tax income appears on the last page of your most recent income tax statement (avis d’imposition), in the “Your references” box.
It serves as an indicator used to determine eligibility for certain social benefits, tax reductions or exemptions, particularly with regard to local taxes, as well as for certain regulated savings products such as the “livret d’épargne populaire” (LEP – a French savings account for low-income individuals).
Reference tax income (RFR) is calculated based on taxable net income.
To arrive at it, one must, among other things, add the following:
- certain tax-exempt income (for example: certain tips received in 2025 or wages of employees posted abroad),
- certain income subject to a final withholding tax (for example: income from equity),
- certain deductible allowances (for example: 40% deduction on dividends),
- certain deductible expenses from income (for example: contributions and premiums for retirement savings plans deducted from total income),
- taxable capital gains from real estate.
Key takeaways
These four terms are not interchangeable: they follow one another in the French income tax calculation. Taxable net income determines what you pay; reference tax income determines what you are entitled to. That is why it can be significantly higher than your taxable income, since it adds back income and allowances that the progressive scale had set aside.
Frequently asked questions
Where can I find my reference tax income?
It appears on the last page of your most recent income tax statement (avis d’imposition), in the “Your references” box.
Why is my reference tax income higher than my taxable net income?
Because it is calculated based on taxable net income, to which certain items are added back: tax-exempt income, income subject to a final withholding tax, deductible allowances such as the 40% deduction on dividends, certain expenses deductible from total income, and taxable capital gains from real estate.
What is the difference between total gross income and total net income?
Total gross income corresponds to the sum of the income, profits and gains received during a calendar year, after applying certain deductions. Total net income is obtained by subtracting certain expenses from total gross income, such as the deductible portion of the CSG, alimony payments or contributions to retirement savings plans.
What is reference tax income used for?
It is an indicator used to determine eligibility for certain social benefits, tax reductions or exemptions, particularly with regard to local taxes, as well as for certain regulated savings products such as the French livret d’épargne populaire (LEP).
Which income is subject to the progressive tax scale?
Taxable net income. Income taxed at a flat rate, such as the single flat-rate withholding tax or the final withholding tax, is not included, unless taxation under the progressive scale has been chosen.
Kind regards
Camilla Nissen MICHELIS
Cabinet Nicolas BRAHIN
Lawyers in NICE
1, Rue Louis Gassin – 06300 NICE (FRANCE)
Tel : +33 493 830 876
Fax : +33 493 181 437
Email : camilla.nissen.michelis@brahin-avocats.com
www.brahin-avocats.com